"Come Back in 2 Years"
Banks and SBA lenders want tax returns, seasoned bank statements, and time in business. You've been open 4 months. There's nothing in the file for an underwriter to say yes to.
Launch Line
Your First Line of Business Credit. Starter business credit for startups and unseasoned businesses
Banks want 2 years of tax returns and 6 months of bank statements. You don't have them yet. Launch Line is underwritten on the owner's personal credit instead—so you can launch, build a business credit profile, and move to conventional financing once you have history to show. Subject to lender approval. Terms vary.
No charge | No obligation | No sales pressure
4-Rung Ladder toReal Business Credit
Where Launch Line fits, and where it hands off
You start on Rung 1. We don't leave you there.
Illustrative. Milestones vary by business. All financing is subject to lender approval. Terms vary.
Launch Line is starter business credit. Not a magic bullet—a proven first rung for businesses that don't have one yet.
The Problem
Conventional lenders underwrite history. A business with no history has nothing to underwrite. That's the whole story—and it traps new owners in a loop.
Banks and SBA lenders want tax returns, seasoned bank statements, and time in business. You've been open 4 months. There's nothing in the file for an underwriter to say yes to.
You have no PAYDEX (your payment performance index across vendors), no trade lines, no business credit file at all. You can't build that profile without credit. And you can't get credit without the profile.
Savings, a home equity draw, a check from family. Resources that should have been working as collateral get spent instead—and the runway you needed in month 8 is gone by month 3.
The Solution
Launch Line flips the underwriting question. Instead of asking what your business has done, it asks what the owner's credit says. Strong personal credit can open business credit accounts—many structured at 0% introductory rates—before the business has a single financial statement to show.
Approves before the business has financials or operating history. The idea doesn't have to be proven yet.
Structured around 0% introductory-rate accounts—up to 24 months interest-free to launch with. Subject to lender approval. Terms vary.
Payment activity reports to the major business credit bureaus—Dun & Bradstreet, Experian Business, and Equifax Business. Every on-time payment builds the profile conventional lenders pull later.
How It Works
Four steps. The first one decides everything.
The conversation starts and ends with the owner's personal credit score. 680+ is the threshold this product is built around. Below that, it isn't the right fit—and we'll say so instead of wasting your time.
First question on the call: what does your personal credit score sit at right now? Lenders typically pull two bureaus and go with the lower score or the average, so we look at the whole picture, not just your best number.Strong personal credit can qualify the owner for multiple business credit accounts carrying 0% interest for up to 24 months. Accounts are opened together so the credit lands as one pool.
Typically $25,000 to $150,000 approved. Subject to lender approval. Terms vary.Funds are available as soon as accounts are open and active. The business has usable business credit with no revenue history required.
Draw as needed—inventory, marketing, payroll, equipment, early hires.The whole strategy is using the interest-free window to launch, generate revenue, and pay the balances down before the promotional rate expires.
A business that launches in month 1 and pays down by month 12 may pay zero interest over the life of the promotional period.What Makes This Different
Most brokers open the accounts, collect the referral fee, and disappear. That's how founders end up carrying a 20%+ balance they never planned for. We work the other end of the timeline.
We track your promotional end dates and your business credit profile from the day the accounts open. You'll know exactly how much runway is left, because that date is the whole ballgame.
Before the promotional period ends—or 3 to 6 months after your business credit score reaches lender threshold, whichever comes first—we work to transition you onto a standard business line of credit, term loan, or other conventional facility. Subject to lender approval. Terms vary.
These accounts report to Dun & Bradstreet, Experian Business, and Equifax Business. Twelve months of clean payment history builds the business credit profile conventional lenders underwrite. That's the asset you're really building.
Why It Matters
Most founders don't fail because the idea was wrong. They fail because they ran the first year underfunded—saying no to things they should have said yes to, moving at the speed their bank balance allowed instead of the speed the opportunity demanded.
Business credit in place changes what you're able to say yes to. Here's what that actually looks like on a Tuesday.
Suppliers price you differently when you can commit to volume and pay on terms. Bulk discounts, better allocation, first call when inventory is tight. The founder with business credit gets a different price list than the founder without it—for the exact same order.
Waiting until you're drowning means hiring whoever is available that week. With business credit in place you hire the person you actually want, on your timeline, and you get them trained before the busy season instead of during it.
Ad spend compounds. The business that starts testing in month 1 knows what works by month 6. The one waiting on revenue to fund marketing is still guessing a year later—and paying more for the same customer.
The other way a pre-revenue business raises six figures is by selling equity—a permanent slice plus someone else's opinion on how you run things. This is debt you repay and walk away from. You own everything you build on top of it.
No more draining savings, tapping home equity, or asking family for a check that changes Thanksgiving. Your personal reserves stay where they belong—as your safety net, not the company's working capital.
This is the part founders underrate. A charge card like American Express demands payment in full every month. These accounts revolve—you carry a balance and pay it down when the cash actually arrives. One slow month doesn't become a crisis.
Equipment at auction. A lease on the right corner. A competitor's customer list. The container that has to be booked this week. Opportunities have expiration dates, and "I'm waiting on funding" is how founders watch them pass.
Every on-time payment reports to Dun & Bradstreet, Experian Business, or Equifax Business—each bank uses its own. Because several accounts open at once, you build a file across multiple bureaus simultaneously. The business credit does two jobs: it funds the launch, and it builds the profile that qualifies you for conventional financing next year. Nothing else at this stage does both.
One thing to know up front: the wholesale lender charges a one-time startup fee of 10% of the approved amount. You never write a check—it's deducted from the approved credit automatically at funding, so a $100,000 approval nets you $90,000 in usable business credit. It's separate from interest, it's disclosed in writing before anything is opened, and LendCraft Capital Advisors LLC charges you nothing for the advisory. Approved amounts and terms are subject to lender approval and vary by applicant.
The Details
The terms, stated plainly, and the four things that keep it running smoothly once you're funded.
All financing is subject to lender approval. Terms and availability vary.
That's it. No bank statements. No tax returns. No financials.
Who You're Talking To
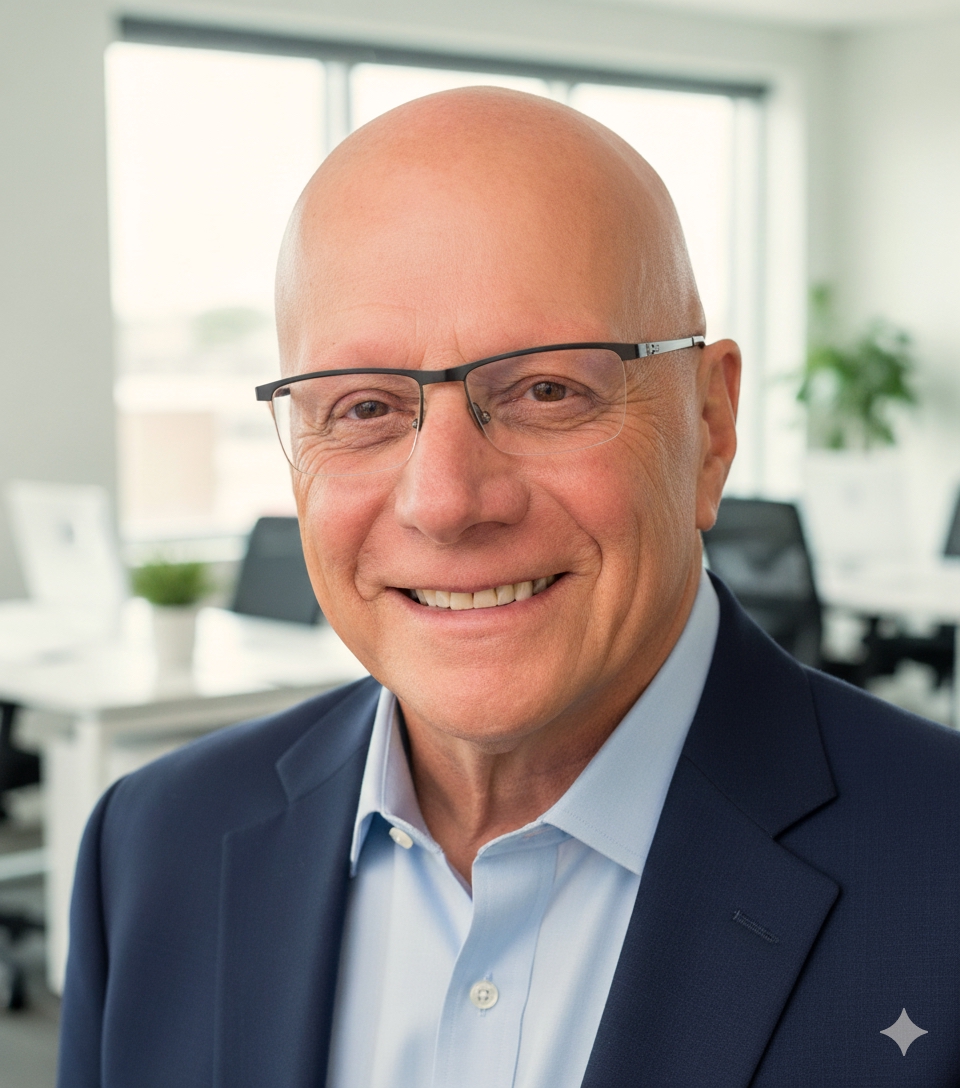
I'm Sal Benti. I spent 30+ years in technology, space, fintech, and telecoms. I raised more than $50 million as an operator and a borrower, scaled one company to $240 million in revenue, and took another to a $2 billion market cap.
I know what an underwriter is looking for because I've been the one asking for business credit. LendCraft Capital Advisors LLC exists to put that lens on your file before a lender ever sees it—and to tell you the truth about which product fits, including when the answer is "not this one."
Proof
"We'd been open 5 months. Every bank wanted 2 years of returns I didn't have. We opened accounts at 0% and put it straight into inventory and ads. By month 11 we were paying it down out of revenue instead of savings, and my business credit file finally existed. The transition conversation started before I even thought to ask about it."
Representative example for illustration. Not a guarantee of results, approval, or terms. All financing is subject to lender approval. Terms and availability vary.
"I opened my insurance agency 3 months ago. LendCraft advised me on the proper setup to prepare for business funding. I'd already run up over $13,000 on my Amex before LendCraft helped me secure $50,000 in business credit. Now I'm building my agency's credit profile to qualify for standard business loans when I'm ready."
Actual client experience, shared with permission. Individual results vary by applicant and lender. Not a guarantee of approval or terms. All financing is subject to lender approval. Terms and availability vary.
Objections
You can. And if you need one card and aren't trying to build a business credit file, do that.
The difference is what you're left holding 12 months later. On your own you get one account, opened alone, and you have no control over which bureaus it reports to. Many cards available to a new business owner report only to the consumer bureaus, which moves your personal FICO and does nothing for your business credit profile.
Launch Line opens several accounts at once through banks selected because they report to business credit bureaus—Dun & Bradstreet, Experian Business, or Equifax Business, depending on the bank. Because each bank uses its own, a multi-account approval builds your file across more than one bureau at the same time. One card can't do that no matter how well you pay it.
So the real comparison is one card and a slightly better personal score, against a funded launch and a business credit file a conventional lender can underwrite next year.
A charge card typically has to be paid in full every month. That's fine when cash flow is steady and brutal when it isn't—one slow month and you're covering the whole balance out of pocket. These accounts revolve. You carry a balance and pay it down on your own schedule during the 0% window, which is what makes it usable for a business whose revenue hasn't stabilized yet.
Understood—and it's temporary. Used responsibly during the 0% window and paid down on time, these accounts build your business credit file as you go. For a brand-new business with no revenue history, it's often the only door that's actually open. If the personal exposure isn't something you're willing to carry, say so on the call and we'll look at what else fits.
That's why we look at your cash flow projections first. If the business can't realistically service the debt inside the promotional window, we'll tell you this is the wrong tool. This product is for founders with a clear plan to generate revenue—not for taking the credit and sitting on it.
It should. That's exactly why the strategy is to use the 0% window, generate revenue, and pay the balances down before it ends. We track the end date with you and work to move you to conventional financing before it arrives. Nobody here benefits from you sitting in high-interest debt.
Not yet. Lenders generally want 6 to 12 months of business revenue history before they'll underwrite a term loan or a standard line of credit. Launch Line is what gets you there. Six months from now, with revenue and a reporting payment history behind you, that conversation looks completely different.
680 or better on the owner's personal credit. That's the threshold this product is built around. Below it, we'll be straight with you and point you toward building the profile first rather than sending you into a decline.
One thing worth knowing before you apply: lenders typically pull two bureaus and use the lower of the two scores, or the average. Scores often differ by 20 to 40 points between bureaus, so if you're sitting at 700 on one and 660 on another, plan around the lower number. If you're close to the line, we'll tell you what to clean up first instead of burning an application.
Next Step
Some founders want to talk it through first. Some already know and want to move. Either door works—and neither one costs you anything.
No charge. No obligation. No sales pressure.
All financing is subject to lender approval. Terms vary.
Start My ApplicationTakes about 10 minutes. Submitting does not apply for credit on its own.
Prefer email? Reach us at [email protected]
Commercial loan referral and advisory for serious business operators and commercial real estate investors.
CONTACT
LendCraft Capital Advisors LLC provides complimentary capital advisory consultations as part of its commercial loan referral services. LendCraft is not a lender, credit counselor, or credit repair organization. Advisory services are provided at no charge. Compensation is received exclusively through referral arrangements with licensed lending partners. All financing is subject to lender approval. Terms, conditions, and availability may vary.